Contact
Current setting: Follow device

Coverage planning

Home insurance calculator

Last updated

Use the home insurance calculator to check your dwelling limit, belongings and deductible. If you have a written quote, turn its annual premium into a monthly budget.

What goes into a rebuild estimate?
A house and its land shown separately The roof and walls form the building above a separate hatched layer of land. BuildingLand

Use the cost of rebuilding the structure. The land’s market value stays separate. See what to include

Dwelling figures

Compare two figures from your own records. Leave unknown amounts blank.

Example scenario

The documented cost of rebuilding the house.

Your current or proposed Coverage A limit.

Use the date on the estimate.

Belongings inventory Optional

Group belongings by room. Enter a quantity and a replacement cost for each row. Mark valuables you want to check against a policy sublimit.

Blank CSV template

Edit the CSV in a spreadsheet. Replace sample entries with your own. Leave out names, addresses, policy numbers and serial numbers.

Downloading entered rows submits the worksheet to the server. The blank template can be downloaded without sending any entries.

Item 1

Item 2

Item 3

Item 4

Item 5

Up to 30 rows. Blank quantities or costs make the total partial. Enter zero only when the value is zero.

Use the contents limit on your policy to compare with the entered belongings total.

Deductible in dollars Optional

Use the deductible that applies to the event you are considering. Your policy identifies its amount or percentage and calculation basis.

For example, wind or hail.

For example, the declarations page or an endorsement. Omit personal identifiers.

Use this field for a fixed deductible.

For a 2% deductible, enter 2.

Use this amount only when it is the stated percentage basis.

Monthly home insurance budget Optional

Use the full 12-month premium from a homeowners quote or renewal notice, including any mandatory policy fees once. Leave either figure blank if you only have one. Exclude mortgage payments, taxes and installment charges.

From your current policy or first written quote.

From the renewal offer or second written quote.

Rebuild estimate, dwelling limit or premium?

A rebuilding estimate comes from your insurer or contractor. A dwelling limit is the amount of coverage shown on your declarations page. A premium is the price your insurer quotes for the policy. Use this homeowners insurance calculator to compare the first two figures, then use the quoted premium to plan your monthly budget.

Two homes with the same dwelling limit can have different premiums. Location, construction and roof characteristics help explain why. Read how the Texas Department of Insurance explains insurance prices.

How can I estimate home insurance costs in my ZIP code?

State comparison tools can give you a starting point. California’s survey shows annual premiums for sample homes in selected ZIP codes. It leaves out certain wildfire surcharges, so a home in the same area can cost more than the sample. In Texas, HelpInsure lets you compare rates and coverage types available in your area. Match the property and coverage details as closely as possible, then ask the insurers you’re considering for written quotes. California homeowners premium survey · Texas HelpInsure

With a written annual premium, you can estimate your monthly home insurance budget. For two consecutive offers, compare the renewal notices line by line to see which limits changed with the price. Suppose your current annual premium is $1,800 and your renewal shows $2,100. That changes the monthly average from $150 to $175, or $25 more each month. Compare the dwelling limits and deductibles on both documents to see whether the price also buys different coverage. Your billing schedule determines what is actually due on each date. Compare your current and renewal premiums

Where to find the numbers to enter

  1. Find the dwelling limit. Check your current declarations page or proposed policy. Match the property address and policy period before copying the figure. The declarations summarize coverages, limits and deductibles; read the relevant endorsements too. TDI's declarations-page guide explains what to look for.
  2. Obtain a separate rebuilding estimate. Ask your insurer or agent for its reconstruction estimate and assumptions. A local contractor can help you discuss construction costs. Record the source and date, and check whether recent improvements are reflected. California's regulator recommends reviewing building characteristics and current local costs. See California DOI's dwelling-limit guidance.
  3. Collect the optional inputs. For the inventory, note the room, item, quantity and cost to replace one item. For a deductible, find its percentage or fixed amount, the amount the percentage applies to, and the event it covers. Do not assume that the same deductible applies to every cause of damage. TDI describes separate deductible entries.

Missing a figure? Leave it blank. The dwelling comparison needs both amounts; entering zero to stand for “I don't know” changes the calculation. You can still complete an independent belongings or deductible section when you have its inputs. Replace the prefilled example values before using a result for your own planning.

Why rebuilding cost can differ from your home's value

A sale price reflects the property market and includes land. Reconstruction focuses on the work and materials needed to rebuild the house. California DOI explains why market value and dwelling replacement cost can differ. Read the residential insurance guide.

That is why this worksheet does not substitute a purchase price, mortgage balance or online real-estate estimate for a documented rebuild figure. Nor does it multiply square footage by an assumed national construction rate. If you have competing estimates, compare their dates, included features and assumptions before deciding which one to enter.

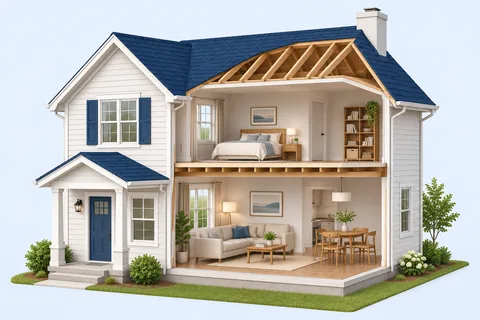
Cutaway of a house showing roof framing and walls around furnished rooms.
The roof and walls belong to the building estimate. Furniture belongs in your inventory. The price of the land is a separate figure.

Keep the parts of a homeowners policy separate

A single policy can contain several coverages. The amounts are not one interchangeable pot of money. The following is a general orientation; your policy defines its terms.

Homeowners policy coverages and what the worksheet measures
CoverageWhat it concernsHow this worksheet handles it
DwellingThe house and attached structures damaged by a covered event.Compares your entered rebuild estimate with your entered dwelling limit.
Personal propertyBelongings such as clothing, furniture and electronics, subject to policy terms.Totals the items you enter and compares them with an optional belongings limit. This is not an insurer's settlement.
Personal liabilityCovered responsibility for injury to another person or damage to their property.Does not calculate a liability limit or assess legal responsibility.
Additional living expensesEligible extra living costs when covered damage makes the home uninhabitable.Does not estimate a temporary-housing allowance.

Detached structures may have their own coverage. These distinctions are described in the Texas home insurance guide.

For additional living expenses, check both the dollar limit and any time restriction. Keep receipts and distinguish extra costs from normal spending. TDI explains when these expenses may be reimbursed.

Which dwelling limit should I enter if my policy has an extension?

Enter the base dwelling limit, often labeled Coverage A on the declarations page. Record any extended replacement cost percentage separately. This endorsement can provide additional funds for qualifying rebuilding costs above the base limit. The policy sets the percentage and conditions. Washington insurance commissioner’s guide to extended replacement cost

Two hypothetical offers for the same $465,000 rebuilding estimate
Figure to checkOffer AOffer B
Base dwelling limit to enter$400,000$450,000
Estimate above that limit$65,000$15,000
Replacement cost extension in this offerUp to 25% of the base limitBase limit only
Base plus stated extension, if applicable$500,000$450,000

In Offer A, 25% × $400,000 gives a maximum additional $100,000 under the assumed endorsement. Entering $500,000 as the base limit would hide the $65,000 difference the worksheet is designed to show. The actual amount available depends on covered rebuilding costs and the endorsement terms.

Before comparing the offers, ask for the endorsement form and the conditions for using the extra amount. Ask the contractor which costs in the estimate are required by current building codes. Then check the policy’s separate ordinance or law provisions, including any dollar limit and whether that limit sits within or above the dwelling amount. California Department of Insurance on building code upgrades

Compare the base dwelling figures in the worksheet

Three examples—and what each result actually means

These are original illustrative scenarios, not recommended coverage amounts or typical household costs.

1. A difference between two dwelling figures

You enter a $425,000 reconstruction estimate and a $400,000 dwelling limit.

Difference = max(0, $425,000 − $400,000) = $25,000

The result identifies a $25,000 difference to discuss. It does not calculate a claim payment. Check whether both figures describe the same property and whether additional policy provisions affect the comparison.

If the estimate were $390,000 with the same limit, this formula would show $0. That would not establish complete protection or automatically justify reducing coverage.

2. A percentage that uses the insured amount

Suppose your policy states a 2% deductible based on a $400,000 dwelling limit for the event being considered.

2%Policy percentage$400,000Specified basis$8,000Example deductible
Use the amount named in your policy for the applicable event.

It is not 2% of a hypothetical $6,000 repair bill, which would be $120. The stated $8,000 deductible exceeds that repair amount in this simplified example. This worksheet translates the deductible; it does not decide coverage or payment. TDI illustrates percentage and fixed-dollar deductibles.

3. A useful total that is still incomplete

You list two living-room sofas at $800 each and one bedroom dresser at $1,200. You also list a camera whose replacement cost you have not checked.

Entered partial total = (2 × $800) + (1 × $1,200) = $2,800

The camera stays unknown. If it costs $450 to replace, entering one at that cost brings the total to $3,250. Against a $3,000 belongings limit, the entered difference is $250. Flag the camera if its coverage may be subject to a special limit; the worksheet does not determine that limit.

Build the belongings total from a real inventory

Walk through each room, including closets and storage spaces. Keep photos or video and identifying details for important items. TDI recommends including overlooked spaces such as garages and keeping the inventory somewhere accessible if the home is damaged. Use TDI's home-inventory guidance.

Enter each item under a room and use a consistent basis for its unit cost. For a pair of identical chairs, enter a quantity of two and the replacement cost of one chair. Keep receipts, serial numbers and photos in your own records. Flag expensive or unusual items to check for special limits in the policy.

Keep an editable copy. In the belongings inventory, download the rows currently in the form, even while quantities or costs are incomplete. The spreadsheet has five columns: room, item, quantity, replacement unit cost in US dollars, and whether to check for a special limit. A blank cost stays blank. The file contains your entries, without totals or policy details.

You can also download a blank inventory template and fill it in offline. Open the CSV as comma-separated UTF-8 text, add one row per item and save your edited copy. Formula-like entries carry a literal “Text: ” prefix. Keep identifying details, photos and receipts in your own records.

Replacement cost and actual cash value change the interpretation

Replacement-cost coverage concerns repair or replacement at current costs. Actual-cash-value coverage can reduce that amount for depreciation, reflecting age and condition. The Texas comparison of replacement cost and actual cash value shows why similar damage can produce different payments.

Check the treatment of the building, roof and belongings rather than assuming that one phrase describes everything. TDI notes that roof coverage can change as a roof ages. Read its roof-coverage guidance. This calculator applies no depreciation schedule and does not convert your inventory into a guaranteed payout.

Turn the result into specific questions

  • A positive dwelling difference: verify the estimate's assumptions and check any replacement cost extension separately. See the two-offer comparison.
  • A zero difference: check estimate quality and policy scope; the formula only compares the two entered amounts.
  • A partial belongings total: fill in missing quantities or unit costs before treating the total as your inventory summary.
  • A large deductible: compare its dollar amount with funds you could actually access, then request quotes for any alternatives you want to compare.

Keep the input source and date with your results. If you change one assumption, compare the before-and-after figures so you can explain what changed.

A coverage amount does not identify every covered loss

Policy terms matter alongside limits. TDI's guide identifies exclusions and restrictions such as wear and tear and earthquake damage, while explaining that coverage varies by policy. Check its coverage overview, then inspect your own contract and endorsements.

Most homeowners policies exclude flood damage. FEMA's National Flood Insurance Program also explains that locations outside high-risk flood areas can still flood. Read FEMA/NFIP's flood-risk guidance. This worksheet does not assess flood exposure, determine whether a water loss qualifies as a flood, or price flood insurance.

Home insurance calculator questions

Dwelling coverage and rebuild estimates

How much is home insurance for a $400,000 house?

Ask an insurer for a quote using the address, building details, coverages and deductible you want. A $400,000 sale price can include land, while a $400,000 dwelling limit describes coverage. Once you have the written annual premium, divide it by twelve to estimate a monthly budget. Find sample prices and compare your renewal · Texas guidance on insurance pricing

Can I use this without a rebuilding estimate?

Yes. You can total your belongings, check a deductible or budget for a written premium with their own inputs. Leave the rebuild field blank until you have a dated estimate and a dwelling limit to compare.

How does the 80% rule in home insurance work?

First look up the replacement-cost condition in your own policy. For a fictional $400,000 rebuild estimate, an 80% condition would correspond to $320,000. A $300,000 dwelling limit falls $20,000 short of that condition and $100,000 short of the full rebuild estimate. Those are different comparisons. Falling below the policy’s threshold can affect a partial loss, while the full rebuild figure still matters if the house is destroyed. The percentage and claim terms depend on the contract. Florida’s explanation of replacement-cost conditions · Texas home insurance guide

Does a $0 dwelling difference mean I am fully insured?

No. It means only that the entered limit is at least the entered estimate. The dwelling example shows why a zero result is not a complete policy assessment.

When should I revisit the figures?

Review the reconstruction inputs after meaningful home improvements and at renewal, and refresh the inventory after significant purchases. California DOI and TDI's inventory guide explain these checks.

Deductibles, belongings and exclusions

Is a 2% home insurance deductible 2% of the claim?

Use the basis stated in the policy. In the example above, 2% applies to the dwelling limit. Check the event and deductible wording before using that calculation for your own policy.

Will insurance pay the belongings total shown here?

The number is the sum of your entries, not a settlement estimate. Valuation terms, coverage conditions and deductibles must be considered separately. The tool does not read your policy.

What should I do about jewelry, art or other valuables?

List them and ask about item-specific limits or additional coverage. An overall personal-property limit does not necessarily resolve those restrictions. TDI discusses limits for valuables.

Can I assume my home policy includes flood protection?

No. Most homeowners policies exclude flood damage. Check your documents for separate flood protection rather than treating a dwelling limit as evidence of flood coverage. See FEMA/NFIP guidance.

How we calculate these figures

Dwelling difference

Subtract the entered dwelling limit from the entered rebuild estimate. Show zero if the limit equals or exceeds the estimate. If either figure is unknown, show no result.

Belongings

Multiply each listed quantity by its replacement unit cost. Add the completed lines by room. An incomplete line makes the subtotal partial. If you enter a belongings limit, compare it with the known inventory amount; a flagged item may have its own limit.

Deductible

Use the fixed amount entered, or multiply the selected basis by the percentage divided by 100. Round dollar results to cents. Verify the event and deductible basis in the policy.

Monthly premium budget

Divide each written annual premium by twelve. To compare a renewal, subtract the current annual premium from the new annual premium, then divide that difference by twelve for the change in the monthly average.

Publisher: Insurance Calculator. This worksheet uses our own examples and arithmetic alongside linked government consumer guidance. AI assisted in preparing the explanations and illustration; no licensed professional review is claimed. See source scope and check date.

Sources and calculation scope

Source review

Official guidance linked beside the explanations was checked on November 5, 2026. State publications provide educational context; your jurisdiction and policy wording govern your coverage. The examples and arithmetic are the publisher’s own illustrations. The cited agencies do not endorse this tool.

Scope of the worksheet

The calculator uses entered values. It does not inspect a policy, verify local construction prices, determine claim eligibility, recommend an insurer, or recommend an amount of insurance.